France E-Invoicing vs E-Reporting: Which Applies to Your Transaction?

France's e-invoicing reform introduces more than one digital compliance flow. A qualifying domestic B2B transaction can require an electronic invoice, while a consumer sale or certain cross-border transaction can require e-reporting instead.
Table of Contents
France's e-invoicing reform introduces more than one digital compliance flow. A qualifying domestic B2B transaction can require an electronic invoice, while a consumer sale or certain cross-border transaction can require e-reporting instead.
Payment information can create another reporting obligation.
For businesses, the difficult part is often not sending the data. It is deciding which regulatory flow applies to each transaction.
The safest way to make that decision is to look at the establishment, customer status, VAT treatment, and transaction type before choosing the reporting path.
E-Invoicing and E-Reporting Are Not the Same
French domestic B2B e-invoicing applies to qualifying transactions between VAT-taxable businesses established in France, where French VAT and French invoicing rules apply.
E-reporting covers defined transactions outside the domestic B2B e-invoicing flow. This includes relevant B2C transactions and certain cross-border transactions, intra-EU acquisitions, and reverse-charge cases.
Payment e-reporting is a third category. It can apply when VAT becomes due on collection for certain services and advances on goods.
A single company can therefore use all three flows.
For example, a French software company may sell subscriptions to French businesses, French consumers, and foreign customers. Its French B2B subscriptions can fall under e-invoicing. Consumer subscriptions can fall under transaction e-reporting where subject to French VAT. A qualifying service payment can also create a payment e-reporting obligation.
The First Question: Where Is the Business Established?
Start with the seller or buyer's establishment.
Domestic French e-invoicing applies to qualifying transactions involving VAT-taxable businesses established in France.
All VAT-taxable businesses established in France and concerned by the reform must be able to receive e-invoices from 1 September 2026. Large enterprises and ETIs must issue and report from that date, while SMEs and micro-enterprises follow no later than 1 September 2027.
Foreign businesses need a separate analysis.
A foreign company without a French establishment for VAT purposes is not subject to the French domestic e-invoicing issuance and receipt obligation. It may nevertheless have e-reporting obligations when French VAT is due on relevant transactions.
Establishment therefore comes before the transaction classification.
The Second Question: Who Is the Customer?
Next, identify the counterparty.
French business customer
If the customer is a VAT-taxable business established in France and the transaction falls within the French B2B rules, domestic e-invoicing applies.
The invoice is exchanged through the regulated e-invoicing architecture using a PA arrangement.
French consumer
A consumer is not a VAT-taxable business. The sale therefore does not enter the domestic B2B e-invoicing flow.
Where the sale is subject to French VAT, the relevant transaction can instead be subject to e-reporting.
B2C reporting can be based on daily aggregated sales data by VAT rate. It should not be treated as sending every consumer invoice one by one through the B2B e-invoicing network.
Foreign customer
A sale to a foreign customer is not automatically a domestic French B2B e-invoice.
The VAT treatment must be assessed.
Exports and exempt intra-EU supplies are generally excluded from transaction e-reporting. Other taxable cross-border operations may require reporting.
This is why a foreign customer alone is not enough to decide the reporting flow.
The Third Question: What Is the VAT Treatment?
Customer status is only part of the answer.
The VAT treatment determines whether a transaction is within the relevant reporting scope.
Consider a French business selling to a company in Germany. This is not a domestic French B2B e-invoice. If the transaction is an exempt intra-EU supply, it is generally excluded from transaction e-reporting.
Another cross-border transaction may have a different VAT treatment and can be reportable.
The same principle applies to exports. Businesses should not classify every foreign sale as e-reportable without checking the VAT treatment.
For domestic transactions, businesses also need to identify whether the transaction is subject to French VAT and whether any exemption or special rule changes the reporting treatment.
The Fourth Question: What Type of Transaction Is It?
The type of transaction adds another layer.
Goods, services, consumer sales, intra-EU acquisitions, reverse-charge transactions, and payments do not necessarily follow the same reporting path.
This is particularly important for payment e-reporting.
A service or advance on goods can require payment e-reporting when French VAT becomes chargeable on collection.
However, payment e-reporting does not apply where the supplier has opted to account for VAT on debits or where the transaction is subject to reverse charge by the customer.
The invoice and payment are therefore separate compliance events.
France E-Invoicing vs E-Reporting: Quick Comparison
| Situation | Main regulatory flow | Important qualification |
|---|---|---|
| French VAT-taxable business to French VAT-taxable business | Domestic B2B e-invoicing | Applies where French VAT and French invoicing rules apply |
| French business to consumer or other non-taxable person | Transaction e-reporting | Applies to relevant transactions subject to French VAT; B2C data can be aggregated daily |
| French business to foreign customer | E-reporting assessment | Some taxable cross-border operations are reportable; exports and exempt intra-EU supplies are generally excluded |
| Service or advance payment where VAT is due on collection | Payment e-reporting | Does not apply where VAT on debits has been elected or reverse charge applies |
| Foreign business without a French VAT establishment | E-reporting assessment | No French domestic e-invoicing issuance/receipt obligation, but e-reporting can apply where French VAT is due |
This table is a starting point, not a replacement for transaction-level VAT analysis.
A Practical Example: SaaS Subscriptions
Consider a French SaaS company.
It sells a subscription to a French VAT-taxable company. That is a domestic B2B transaction and can fall under e-invoicing where the French VAT and invoicing conditions apply.
The same subscription is sold to a French consumer. The transaction is not a domestic B2B e-invoice. Where subject to French VAT, it can fall under transaction e-reporting.
Now consider a customer in Germany. The transaction needs a VAT assessment. If it is an exempt intra-EU supply, it is generally excluded from transaction e-reporting. Another cross-border transaction may require reporting.
Product type alone does not determine the reporting flow. The establishment, customer status, VAT treatment, and transaction type all matter.
What About Payment Reporting?
Payment reporting can sit alongside e-invoicing.
A French professional services company may issue a qualifying domestic B2B invoice. If French VAT becomes due on collection, the later payment may create a payment e-reporting obligation.
That applies where the relevant VAT-on-collection conditions are met and the VAT-on-debits and reverse-charge exceptions do not apply.
Businesses therefore need payment data as well as invoice data.
This is one reason an e-invoicing project should not be designed only around invoice generation.
How Should Businesses Automate Classification?
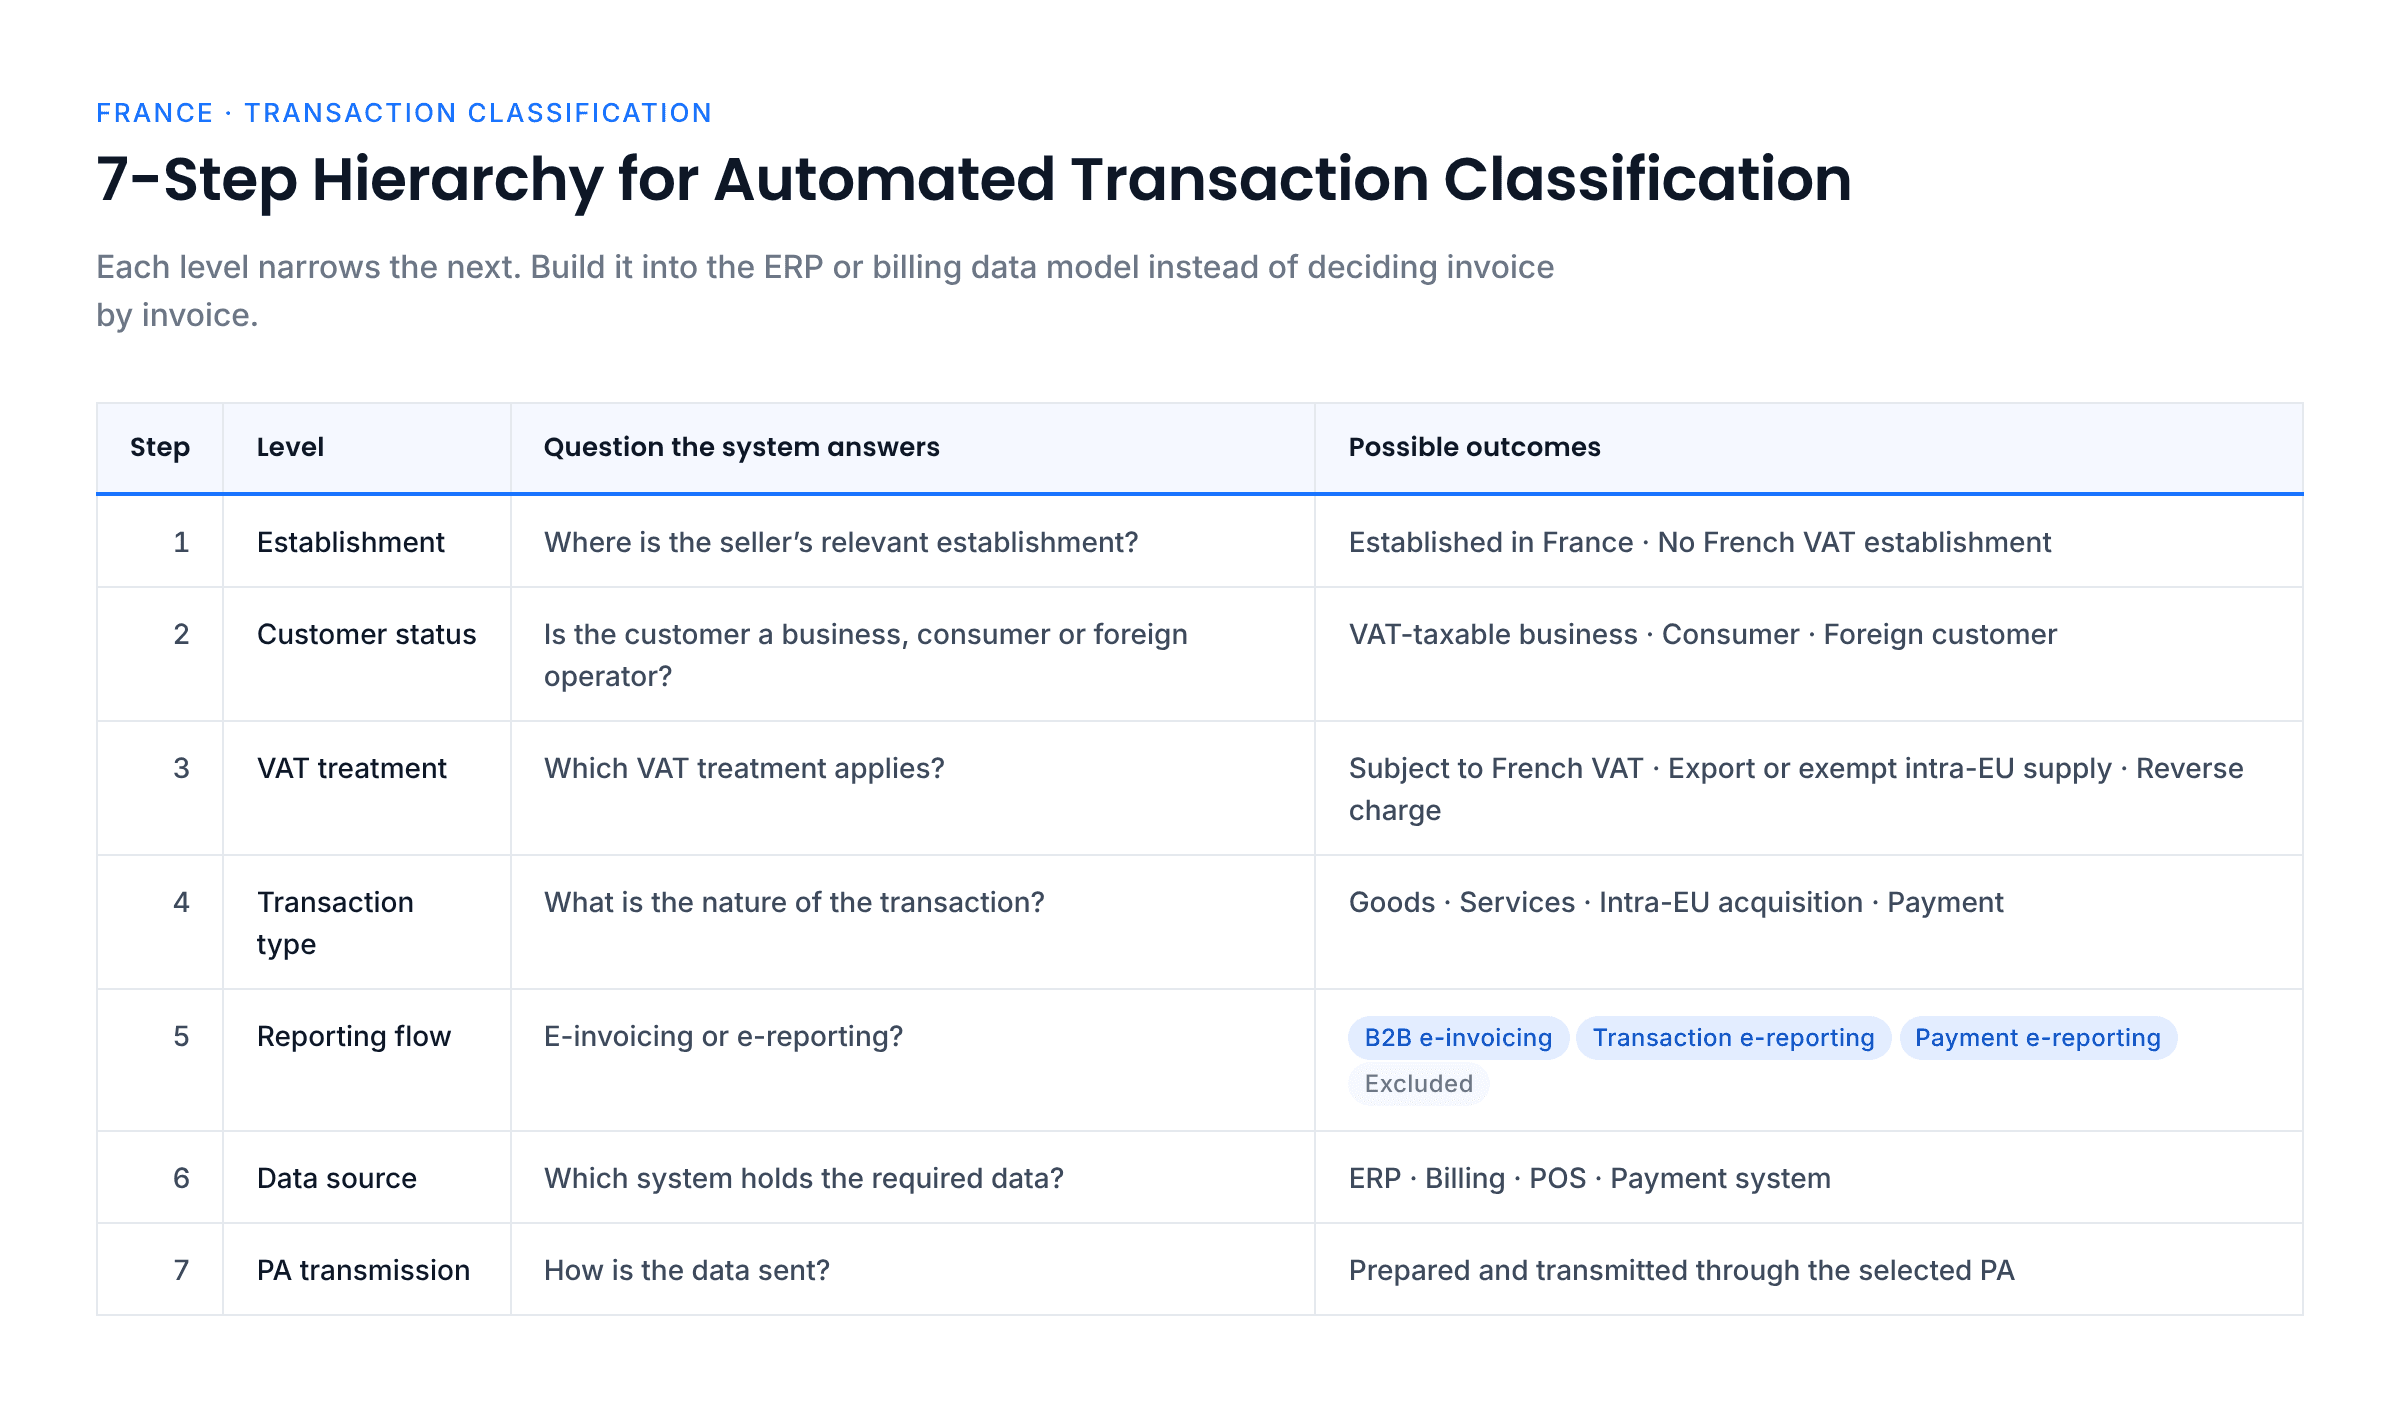
Transaction classification should be part of the ERP or billing data model rather than resolved manually for every invoice.
A useful classification hierarchy is:
- Establishment
- Customer status
- VAT treatment
- Transaction type
- Reporting flow
- Data source
- PA transmission
For example, the ERP can identify the seller's establishment and customer type. Tax rules can determine the VAT treatment. The transaction engine can classify the flow. The appropriate data can then be prepared for the selected PA.
The business remains responsible for the tax treatment and the completeness of the data sent. PA transmission does not transfer that responsibility.
What Happens With Mixed Customer Bases?
Businesses with both B2B and B2C customers should not build one reporting rule for the entire customer base.
The same product or service can follow different reporting paths depending on the customer and VAT treatment.
A French SaaS subscription sold to a French VAT-taxable company may enter domestic B2B e-invoicing. The same subscription sold to a French consumer may enter B2C transaction e-reporting. A sale to a German VAT-registered company needs a separate VAT analysis and may be excluded if it is an exempt intra-EU supply.
The classification needs to happen at transaction level.
How Does a PA Fit In?
Businesses use a Plateforme Agréée, or PA, for regulated e-invoicing and applicable reporting flows.
A compatible e-invoicing solution can connect ERP and other business systems to the PA. The platform can support data mapping, validation, workflow, and integration, while the PA provides the regulated exchange layer.
When selecting a solution, businesses should understand which legal entity holds the PA registration and how the solution connects to that PA.
How Complyance Can Help
Businesses can use Complyance as a technology layer to connect existing systems with the required French e-invoicing infrastructure.
The practical focus is to bring relevant invoice, transaction, customer, and payment data into a controlled process, apply validation and classification logic, and prepare the appropriate data for the regulated flow.
The exact PA arrangement should be confirmed during implementation so the business understands how Complyance connects to the selected PA and which flows are supported.
A Simple Classification Checklist
Before sending data, ask:
- Is the relevant business established in France?
- Is the customer a VAT-taxable business, consumer, or other non-taxable person?
- Is the transaction subject to French VAT?
- Is it a domestic B2B transaction?
- Is it B2C?
- Is it cross-border?
- Is it an export or exempt intra-EU supply?
- Is it an intra-EU acquisition or reverse-charge transaction?
- Does payment e-reporting apply?
- Is VAT due on collection?
- Has VAT on debits been elected?
- Which system contains the required source data?
- Which PA arrangement will handle the regulated transmission?
Conclusion
The difference between France e-invoicing and e-reporting comes down to the transaction, not simply the invoice.
Businesses need to identify the establishment, customer status, VAT treatment, and transaction type before deciding which regulatory flow applies.
Once that classification is built into the business systems, the PA can handle the regulated transmission layer. For companies with complex B2B, B2C, and international activity, this approach creates a much more reliable foundation for French e-invoicing compliance.
Frequently Asked Questions
Qualifying domestic B2B transactions between VAT-taxable businesses established in France can fall under e-invoicing where French VAT and invoicing rules apply.
No. The VAT treatment matters. Exports and exempt intra-EU supplies are generally excluded, while other taxable cross-border transactions may be reportable.
Yes. A business can issue domestic B2B e-invoices while reporting relevant B2C and cross-border transactions separately. Payment e-reporting can also apply where the conditions are met.
No. Relevant B2C sales subject to French VAT are generally handled through transaction e-reporting.
A foreign company without a French VAT establishment is not subject to the domestic French e-invoicing issuance and receipt obligation, but it may have e-reporting obligations where French VAT is due.
About the Author
Swathy
Content Marketer
I’m a Content Marketer at Complyance, focused on e-invoicing. Over the years, I’ve created a wide range of content, including blog posts, whitepapers, and product guides, which have supported Complyance’s growth across markets such as the UAE and EU regions. My goal is to deliver content that is comprehensive, clear, accurate, and easy to understand, no matter how complex the topic.